Mortgages · Rentals · Car loans
Is your credit report even right?
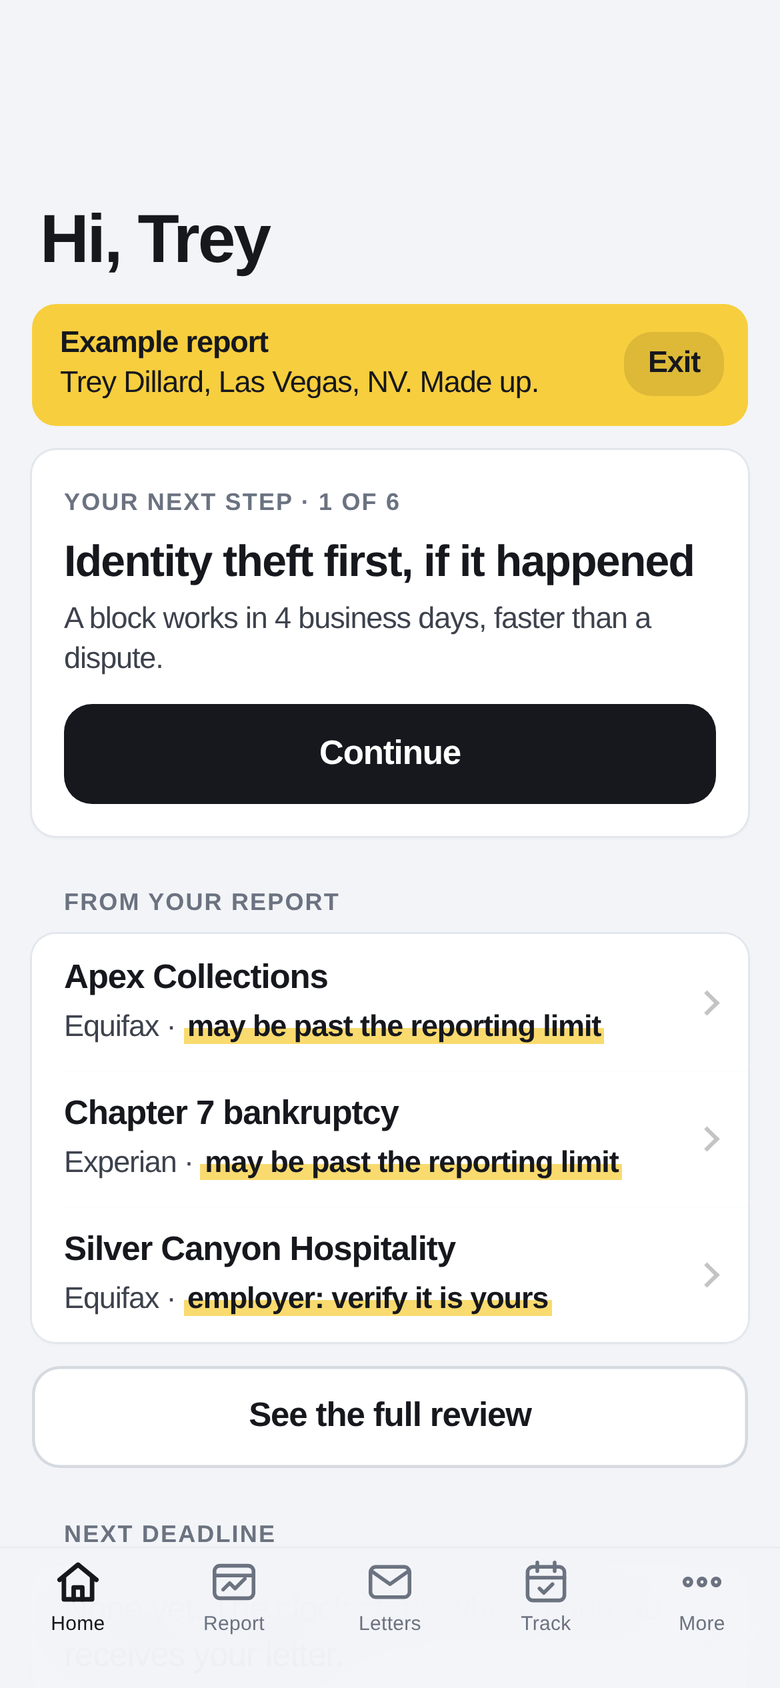
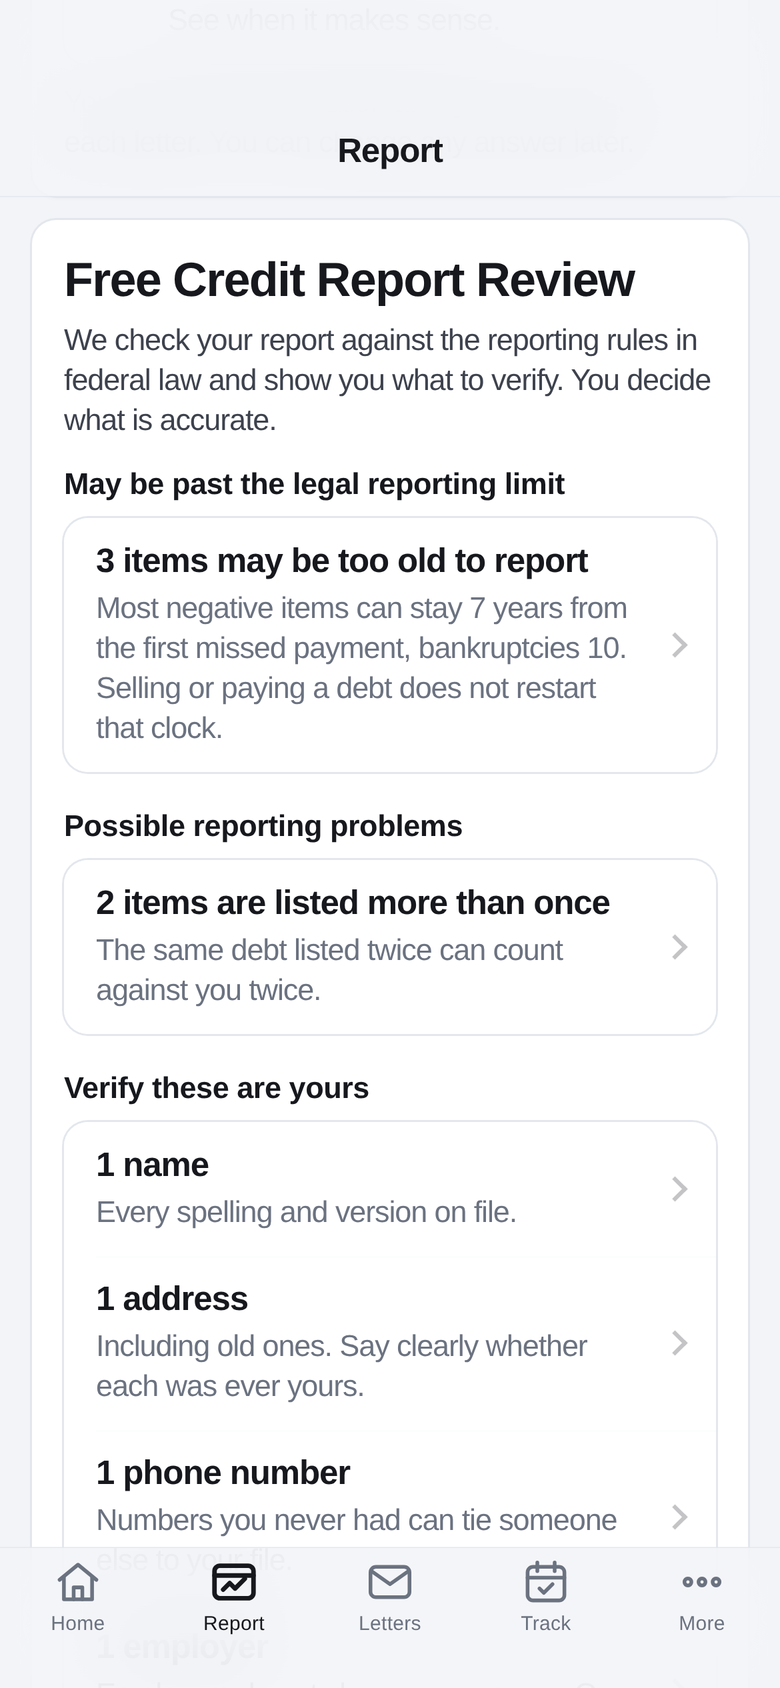
Old debts still showing after 7 years. Balances you already paid. Accounts you don’t recognize. 1 in 5 people have a mistake on at least one of their reports.1 ZungiDill reviews yours free, on your phone, and drafts the letters to dispute what is wrong.
The problem
The system is the hard part.
found at least one mistake
In a 2024 Consumer Reports and WorkMoney study, 44% of people who checked their reports found at least one error, most often wrong personal details or accounts they did not recognize.2
of CFPB complaints
Credit and consumer reporting made up 85% of the 3.2 million complaints the CFPB received in 2024, the largest category by far.3
days, per letter, per bureau
The usual route is paper: a letter to each bureau, your Social Security number written by hand, certified mail, a 30-day wait, then a form reply. Paid services charge monthly and keep your data. Doing it alone means carrying every step.
Medical bills on your report?
Under the credit bureaus’ own policies, paid medical collections and medical collections under $500 should not appear on your reports, and new medical debt is not reported for its first year.4 These are voluntary bureau policies, not a federal law, and some states go further. If one is on your report anyway, you can dispute it.
The fix
The correct process, with nothing extra.
- Nothing uploaded. Your report is read on your phone and the file is not kept. No account, no server, no Social Security number stored.
- Checked against the law. The 7 and 10-year reporting limits, debts listed twice, dates reset after a debt was sold, personal details that are not yours.
- Kept consistent. The same account cannot be “not mine” on one bureau and “mine” on another. ZungiDill stops the contradiction before it reaches a letter.
- One letter per bureau, citing the law that applies. Drafted free from your own answers. No templates to fill in.
- The clock, counted for you. From the day the bureau receives the letter, with a reminder before it runs out.
- The reply, read for you. Photograph it. ZungiDill shows what happened to each item and drafts the next step, free.
What the law requires: if a bureau cannot verify a disputed item, or finds it inaccurate or incomplete, it must delete or correct it (15 U.S.C. § 1681i(a)(5)(A)). Bureaus usually have 30 days to finish.
Applying for a mortgage, apartment or car loan soon? Lenders often check all three reports. A dispute usually takes about 30 days from when the bureau receives it, so start well before you apply.
Pricing
The review and every draft are free. You pay only to print, save or send a finished letter. Replies and follow-up letters are always free.
How many letters do I need?
One letter covers every item you dispute at one bureau. Eight items spread across Equifax, Experian and TransUnion means 3 letters: $14.97 at the launch price. ZungiDill Monthly covers all three bureaus plus letters to the companies, for $19.99 a month for the first 3 months (new subscribers).
Identity theft block letters and letters sent directly to a company are separate letters.
Prices in US dollars, charged by Google Play or the App Store. Monthly renews automatically until you cancel in your store account. See the Terms of Use.
Sources
- Federal Trade Commission, study of credit report accuracy, February 2013: one in five consumers had an error on at least one of their three reports; 5% had errors that could mean less favorable loan terms.
- Consumer Reports and WorkMoney, Credit Checkup study, reported May 2024. Participants were volunteers, not a random sample.
- Consumer Financial Protection Bureau, Consumer Response Annual Report, May 2025 (covering 2024).
- Equifax, Experian and TransUnion voluntary medical debt policies (2022–2023). A CFPB rule that would have removed most medical debt from reports was vacated by a federal court in Texas in July 2025. See this September 2026 summary.